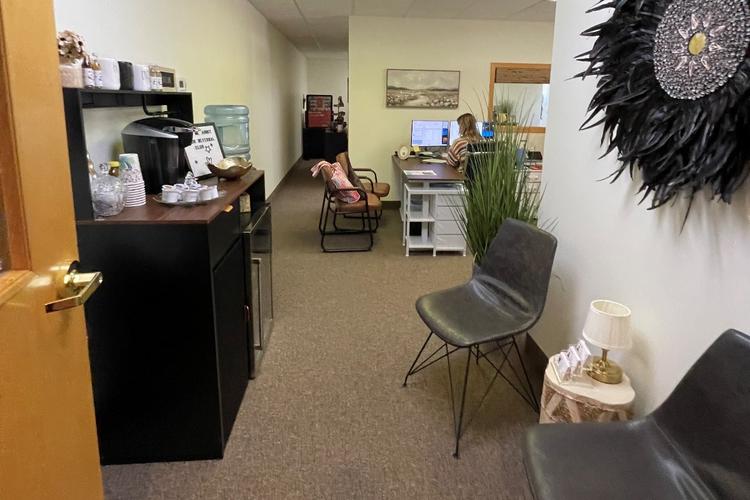
💛 Welcome to the Tammie Downare Agency — State Farm Insurance in Sartell, MN
I'm Tammie Downare, a State Farm insurance agent in Sartell, Minnesota, helping families, individuals, and small businesses across Stearns and Benton County protect what matters most since 2001.
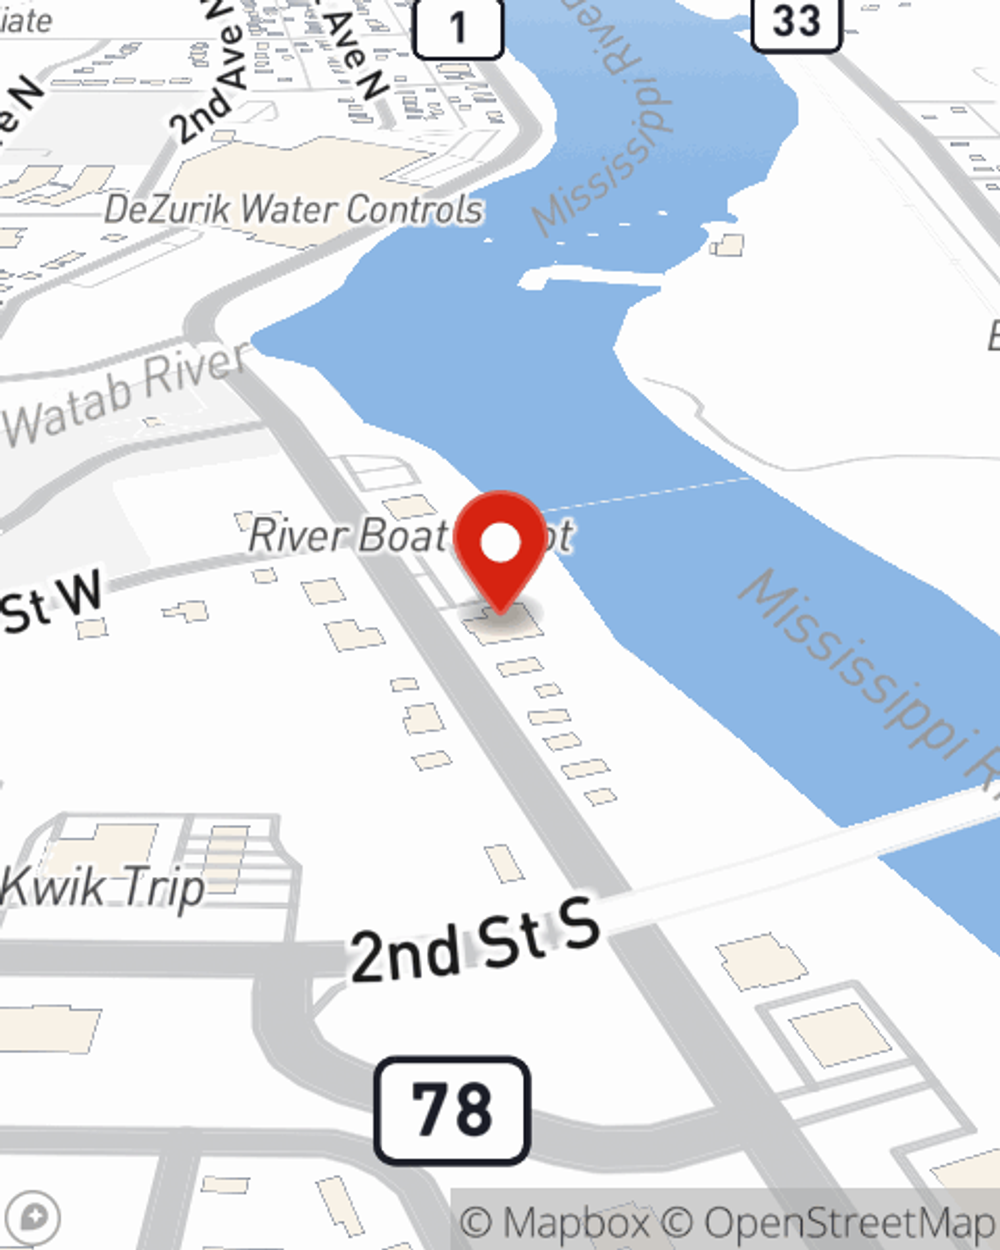
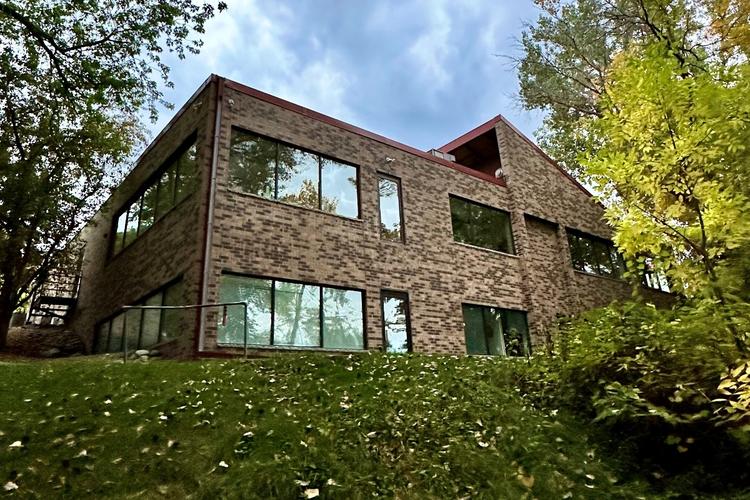
· 📍 Located: 18 Riverside Ave S, Sartell, MN 56377 — next to River Boat Depot and about a block from Watab Park
· 🛡️ Coverage: Auto, home, renters, life, business, umbrella, and personal articles
· 🗺️ Serving: Sartell, St. Cloud, Sauk Rapids, Waite Park, St. Joseph, Rice, Foley, and St. Augusta, along with communities throughout Stearns and Benton County
· 📅 In business since: January 2001, with more than 30 years of State Farm experience
· ⭐ Rated: 4.8 stars by more than 200 neighbors on Google
What makes this office different? We listen first. We take the time to understand your story, your family, your work, and the things that matter most to you — then help you build protection around your real life.
With a local office and a real person on the other end of the conversation, you get personal service backed by State Farm. Our goal is simple: help you understand your coverage, feel confident about your choices, and have someone in your corner as life changes.
Insurance Questions We Answer:
Can reporting damage or an accident affect my insurance rates? Not necessarily! Your rates may change depending on the type of incident, responsibility for the accident, and your previous claims history. See below for more information.
Why Is My Insurance Going Up? Insurance rates can increase even if you haven't reported any accidents or damage, due to rising repair costs, medical expenses, and overall insurance costs. See below for more information.
What Is Coverage S on My State Farm Auto Insurance? Coverage S is optional auto insurance coverage that provides a financial benefit if someone specifically insured under this coverage suffers accidental death or certain serious injuries from a car accident. See below for more information.
🍂 November in Sartell means deer season, colder mornings, and the first real signs that a Minnesota winter is settling in.
As deer become more active and daylight gets shorter, November is a good time to understand how comprehensive coverage applies if your vehicle and a deer cross paths. It’s also a natural time to look over your home or renters coverage before snow, freezing temperatures, ice dams, and frozen pipes become part of the winter conversation.
🚗 On the road: Review comprehensive, collision, rental car, and emergency road service options before winter driving settles in.
🏠 At home: Take another look at your dwelling coverage, roof information, deductible, and how your policy addresses winter-related water damage.
🧣 For renters: Know what your policy says about your belongings and temporary living expenses if a covered loss makes your rental uninhabitable.
November’s Sartell community calendar also reflects something I love about this area: local people and organizations staying connected as the seasons change. The Sartell Chamber’s November activities include a monthly gathering featuring United Way of Central Minnesota along with Coffee Connect, creating opportunities for local businesses and community partners to stay connected as we head toward the holidays.
A few minutes now can help you feel more prepared and confident before winter gets into full swing. Call us today—we’d love to hear from you!
💛 About Tammie
Hi, I'm Tammie. Here's a little of my story — because I'm going to ask you for yours. 😊
I earned my degree from Bemidji State University in psychology, elementary education, and business — a combination that turns out to be made for this work. The way I describe it: I was trained to listen, diffuse, and manage. Therapist, kindergarten teacher, and business owner, all in one.
I spent two years at State Farm corporate and four years as a team member in another agency before opening my own doors in January 2001 — more than 30 years with State Farm all told. Thirty years in, the reason I still love this hasn't changed: people forget about awards, but they never forget the extra time you took, or that you remembered something important to them.
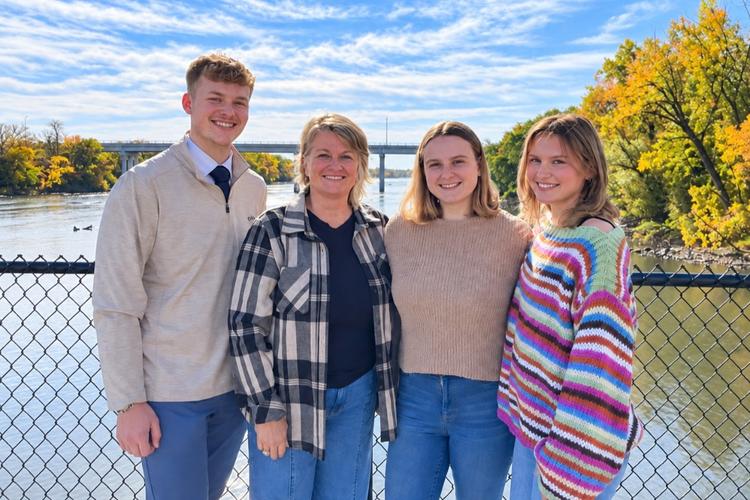
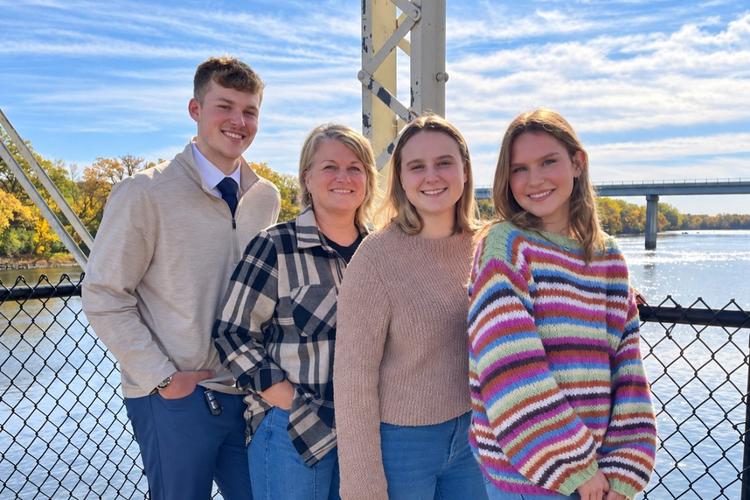
🏡 A little about my life outside the office: I've been married more than 40 years and I'm a proud mom of four — including Trinatie, who is now part of this team (yes, really 💛). Outside of work you'll find me crafting, fly fishing, making art, reading, or planning the next trip. Before insurance I was a portrait photographer, which probably explains why I notice the details.
🤝 Why community matters here: I serve on boards, support local businesses, schools, athletic clubs, and arts organizations, and I speak up for women in business — from lived experience. I came into this industry 30 years ago as a woman in a largely male field. My solution? Show up and wear heels. 👠 Giving back here isn't for show. It's who I am.
📍 Where we work: Our office sits on the Stearns County side of Sartell, right where the Mississippi runs through town. Proudly serving Sartell, St. Cloud, Sauk Rapids, Waite Park, St. Joseph, Rice, Foley, and St. Augusta, and communities throughout Stearns and Benton County, since 2001.
🔍 The Problem We Solve: Most people don't think about their insurance until something goes wrong — a deer on the highway, a hailstorm, a life change that quietly leaves a gap nobody caught at renewal. My team and I make sure that doesn't happen to you. We check in, we review, and we make sure your coverage keeps up with your life.
🛡️ What We Cover
· 🚗 Auto — Minnesota no-fault coverage, deer season comprehensive, Drive Safe and Save, and young driver programs
· 🏠 Home and Renters — replacement cost, hail and wind, ice dam, water backup, and home systems protection
· 💛 Life —life insurance options for families and business owners
· 💼 Business — Business Owner's Policy, commercial auto, workers' compensation, and professional liability
· ☂️ Umbrella and Personal Articles — extra liability protection and coverage for recreational vehicles, jewelry, hunting equipment, and more
Frequently Asked Questions (FAQ)
Does auto insurance cover hitting a deer in Minnesota? Damage from hitting a deer is generally handled under comprehensive coverage, subject to the terms, limits, and deductible of your policy. November is a good time for drivers in Sartell, St. Cloud, Sauk Rapids, and surrounding areas to check whether comprehensive coverage is included before deer activity and winter driving overlap.
What auto coverage should I review before winter driving starts in Central Minnesota? Before snow and ice become part of the daily commute, review comprehensive, collision, rental car, and emergency road service options. Your needs may look different depending on your vehicle, commute, and how much you drive around Sartell and the St. Cloud area.
Does Minnesota no-fault coverage mean my car is covered no matter who causes an accident? No. Minnesota's no-fault system applies to certain injury-related benefits and does not mean damage to your vehicle is automatically covered regardless of fault. Collision, comprehensive, liability, and other coverages each serve different purposes, so it helps to understand what is included in your policy.
What should I check on my homeowners coverage before the first heavy snow in Sartell? Fall is a good time to review your dwelling coverage, roof information, deductible, water-related options, and what it could cost to rebuild your home today. A quick review can also help you understand how your policy addresses common Minnesota winter concerns such as ice dams and frozen pipes.
Does homeowners coverage pay for damage from an ice dam? Coverage for ice-dam-related damage depends on the policy and what caused the damage. Because ice dams can affect roofs, attics, walls, and ceilings during a Minnesota winter, ask how your specific policy addresses resulting water damage, exclusions, and maintenance-related issues.
Does homeowners coverage include flooding from the Mississippi River or melting snow? Standard homeowners policies generally do not cover flooding from rising surface water, including river flooding and some snowmelt situations. Homeowners near the Mississippi River or other waterways in Stearns and Benton County can review separate flood coverage and ask how their policy handles other types of water damage.
Does my landlord's coverage protect my belongings if I rent in Sartell or St. Cloud? A landlord's policy generally protects the building, not a renter's personal belongings. Renters coverage can include protection for personal property and liability, with coverage depending on the policy and circumstances.
I'm leaving my Minnesota apartment for the holidays. What should I check before I go? Review your renters policy and any responsibilities you have for protecting the unit during cold weather, especially when temperatures could lead to frozen pipes. It is also a good idea to understand what your policy says about personal belongings and temporary living expenses if a covered loss makes the rental uninhabitable.
Is the coverage I get through work enough to protect my family? Workplace coverage can be a helpful starting point, but the amount and whether you can keep it after changing jobs can vary. Reviewing your household income, dependents, debts, and long-term responsibilities can help you understand whether additional family protection may be worth considering.
When should I review the coverage that helps protect my family financially? A new baby, marriage, job change, new home, income change, or change in who depends on you can all be good reasons for a review. Even without a major milestone, checking beneficiaries and current coverage periodically can help make sure your protection still reflects your family and responsibilities.
Common Insurance Questions Answered by Tammie Downare:
What Is Coverage S on My State Farm Auto Insurance?
Have you ever looked at your auto insurance policy and wondered, "What in the world is Coverage S?"
You're not alone! Insurance policies have a way of making something fairly simple sound complicated. So, let's make this one a little easier to understand.
Coverage S is an optional benefit on State Farm auto insurance that provides additional financial protection if someone specifically insured under this coverage dies or suffers certain serious injuries in a motor vehicle accident.
Think of it as a little extra financial protection for the unexpected. It's similar in some ways to accidental death insurance, but it is not a replacement for a traditional life insurance policy.
How Does Coverage S Work?
Coverage S is designed to provide a benefit for an accidental death or certain specified injuries, including the loss of a hand, foot, or eyesight, resulting from a covered motor vehicle accident.
There are two coverage amounts to choose from:
$5,000 in coverage
$10,000 in coverage
Here's an interesting feature: Under applicable policy provisions, benefits may double when the insured person is occupying a private passenger car and properly wearing a seat belt at the time of the accident.
For example, a covered accidental death benefit of $10,000 could increase to $20,000 if the seat-belt benefit requirements are met.
The amount paid for a covered injury depends on the specific injury and the policy's benefit schedule. Not every injury qualifies, and not every covered injury receives the full selected amount.
Does Everyone in My Household Have Coverage S?
This is an important detail!
Each person you want covered must be individually listed for Coverage S. It doesn't automatically extend to everyone in your household simply because they're on your auto insurance.
In many household situations, Coverage S may only need to be added to one insured vehicle rather than every vehicle. Our team can review how your policies are set up and confirm that everyone you intend to include is properly listed.
Frequently Asked Questions About Coverage S
Is Coverage S the same as life insurance?
No. Coverage S provides limited benefits for certain accidental deaths or specified injuries involving motor vehicles. Traditional life insurance is a separate type of protection with different terms and benefits.
Does Coverage S cover any injury from a car accident?
No. It applies to specific types of serious injuries defined in the policy, not every injury that may occur in an accident.
Do I need Coverage S on every vehicle?
Not necessarily. Depending on how your household's policies are arranged, coverage on one vehicle may be sufficient. We can help you verify the appropriate setup.
Let's Make Sure You Understand Your Coverage
Sometimes it's the smaller details in your insurance policy that raise the biggest questions.
At my State Farm office in Sartell, Minnesota, my team and I enjoy taking the time to explain those details so you can make informed decisions about protecting yourself and the people who matter most.
Have questions about Coverage S or want to see whether it's included in your current policy? Give us a call. We'd love to help you understand your options!
Will My Insurance Go Up If I File a Claim?
By Tammie Downare, State Farm Insurance Agent | Sartell, MN
"Will my insurance go up if I file a claim?"
It's a question we hear in our office, and I completely understand why people ask. Nobody wants an unexpected increase in their insurance costs, especially when they're already dealing with damage to their car or home.
The short answer? Not necessarily! Filing an insurance claim doesn't automatically mean your rates will increase.
Whether a claim affects what you pay depends on several factors, including the type of claim, who was responsible, your claims history, and how your insurance company determines rates.
Let's talk about what that means.
Not All Insurance Claims Are Treated the Same
Imagine you're driving through Central Minnesota when a deer suddenly runs onto the road. That's a different situation from being involved in a collision with another vehicle.
Insurance companies may evaluate those claims differently.
Some of the factors that can affect your insurance costs after a claim include:
The type of claim: Different types of damage or accidents may be evaluated differently.
Who was at fault: Responsibility for an accident may influence how a claim affects your rate.
Your claims history: Previous claims may be considered when determining future insurance costs.
Other rating factors: Changes in insurance rates, your coverage, or other circumstances may also affect what you pay.
The important thing to remember is that every situation is different.
Should I Talk to My Insurance Agent Before Filing a Claim?
When appropriate, having a conversation with your agent can be a helpful first step.
For example, if you're dealing with damage to your vehicle, we can help you understand your deductible, review the coverage listed on your policy, and explain the claims process.
Knowing those details can help you make a more informed decision.
Of course, certain situations require prompt reporting. If an accident involves injuries, other people, or circumstances that require notification under your policy, it's important to follow those reporting requirements. Don't delay necessary reporting because you're concerned about a possible rate change.
And while we'd love to give you a definite answer about what will happen to your insurance costs, we can't guarantee whether a particular claim will affect your rate.
Frequently Asked Questions About Filing Insurance Claims
Will my insurance increase if an accident wasn't my fault?
Not necessarily. Whether your rate changes depends on the circumstances, applicable insurance rules, and your company's rating practices.
Should I file a claim if the damage is minor?
It depends on the situation. Your deductible, the cost of repairs, applicable coverage, and any reporting requirements are all worth considering.
Can my insurance agent tell me exactly how much my rate will change?
Not always. We can help explain the factors involved, but future rate changes cannot be guaranteed in advance.
Have Questions? We're Here to Help.
Insurance decisions can feel overwhelming when something unexpected happens. My goal is to make sure you understand your options rather than feel like you're making a decision in the dark.
At Tammie Downare State Farm in Sartell, Minnesota, my team and I are happy to help our neighbors throughout Central Minnesota with coverage questions and information about the claims process.
If you're wondering what to do after an accident or have questions about filing a claim, give our office a call. We'd be happy to talk it through with you!
Why Is My Insurance Going Up?
By Tammie Downare, State Farm Insurance Agent | Sartell, MN
"Why is my insurance going up? I haven't had any accidents or filed any claims!"
I get it. You've been paying your insurance, driving carefully, taking care of your home, and doing everything you're supposed to do. Then your renewal arrives, and the cost has increased.
It's frustrating, especially when nothing seems to have changed.
Here's something many people don't realize: Your insurance rates can change even when you haven't filed a claim or made any changes to your policy.
That's because insurance costs are influenced by more than your individual history. They're also affected by the cost of repairs, medical care, and claims occurring across a much larger group of policyholders.
What Causes Insurance Rates to Increase?
There are several reasons your auto or homeowners insurance costs might change.
1. Repairs are becoming more expensive.
Today's vehicles have increasingly sophisticated technology, including cameras, sensors, and safety systems. Even repairs that seem relatively minor can be costly.
Home repairs can also become more expensive as labor and building material costs change.
2. Medical expenses can affect insurance costs.
When accidents result in injuries, the cost of medical care can influence what insurance companies pay for claims.
3. Claims in your area can affect rates.
Here in Central Minnesota, we're familiar with hailstorms, icy roads, and deer crossing the highway.
When insurance companies experience more claims or higher claim costs, those trends can influence insurance rates, even for people who haven't personally experienced a loss.
4. Other factors may have changed.
Your vehicle, driving habits, location, coverage selections, discounts, and other rating factors can influence what you pay.
Is There Anything I Can Do to Help Lower My Insurance Costs?
Possibly! And this is where reviewing your insurance with your agent can be helpful.
When you contact our office, we can look at several things together:
Available discounts: Are you receiving the discounts you currently qualify for?
Multiple policies: Could combining eligible home and auto policies provide a discount?
Coverage options: Does your current coverage still fit your needs?
Deductibles: Would a different deductible make sense for your situation?
Life changes: Has anything changed that should be reflected in your policy?
Keep in mind that adjusting coverage or increasing a deductible can change the protection you have or the amount you would pay yourself after a covered loss. Saving money shouldn't mean making changes you don't fully understand.
Not every review will result in a lower rate, but it can help you understand what you're paying for and whether there are options worth considering.
Frequently Asked Questions About Insurance Rate Increases
Can my insurance go up even if I've never filed a claim?
Yes. Insurance rates are influenced by both individual factors and broader costs, including repairs, medical expenses, and claim activity.
Does an increase mean something changed with my coverage?
Not necessarily. Your rate can change even when your coverage remains the same. Reviewing your renewal can help you understand what's different.
Can my State Farm agent help me find ways to save?
Yes! Our office can review your coverage, check for available discounts, and explain options that may help manage your insurance costs. Eligibility and actual savings vary.
Let's Take a Look Together